Dutch Tax Calculator 2026 Mortgage: How Much Tax Can You Save?
The Dutch tax calculator 2026 mortgage check helps homeowners see how much tax they really save on their home loan. In the Netherlands, a mortgage does not only cost interest. It can also lower your income tax. This guide explains how it works in plain words, with a real example.
What Is Mortgage Interest Deduction in the Netherlands?
Mortgage interest deduction is called hypotheekrenteaftrek. If you own the home you live in, you can subtract the interest you pay from your taxable income in Box 1. Lower taxable income means lower tax.
The deduction is not unlimited. For 2026, the maximum deduction rate is 37.56%. This is the same as the second tax bracket. Even if you earn above €78,426 and pay 49.50% on the top part, you still get only 37.56% back on your interest.
Who Can Use It in 2026?
You can usually claim the deduction if:
- The home is your main residence.
- The loan is for buying, building or improving that home.
- The mortgage is an annuity or linear loan.
- The term is 30 years or less.
Interest-only loans taken out after 2012 generally do not qualify for the deduction. Always check your own loan type with your lender.
What Is the Eigenwoningforfait?
The eigenwoningforfait is a small amount added to your income because you own a home. It is based on your WOZ value, which is the value your municipality gives your home. For most homes in 2026, it is 0.35% of the WOZ value.
So the real benefit is not your full interest amount. It is your interest minus the eigenwoningforfait.
Net deduction = mortgage interest paid – eigenwoningforfait
Real Example: How Much Do You Save?
Let us take a simple case.
- Mortgage: €350,000
- Interest rate: 4%, so about €14,000 interest per year
- WOZ value: €400,000
- Eigenwoningforfait: €400,000 × 0.35% = €1,400
Net deduction: €14,000 – €1,400 = €12,600
Tax saving: €12,600 × 37.56% = about €4,733 per year, or roughly €394 per month.
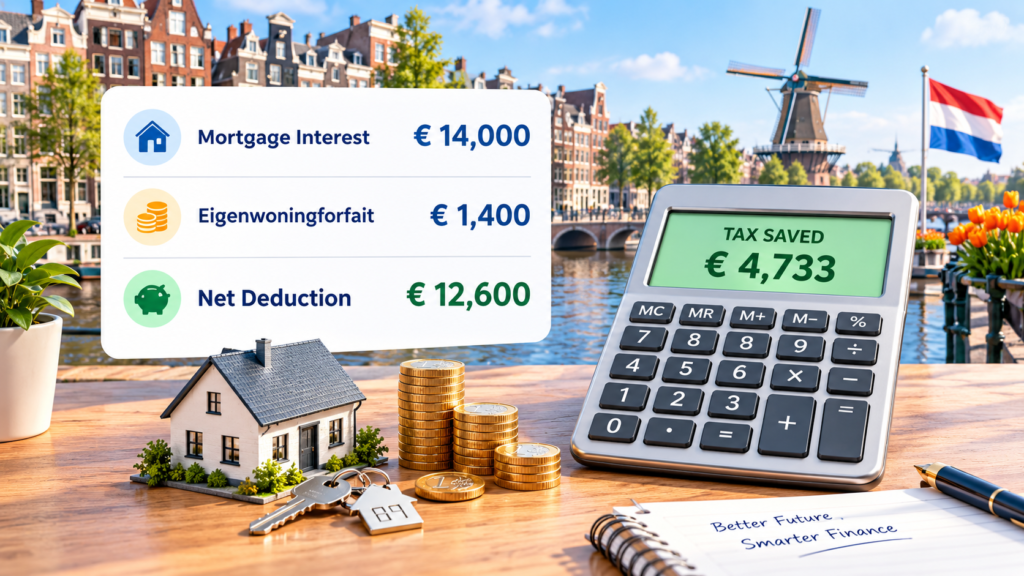
This is an estimate for an annuity loan in the first years, when interest is highest. The real number changes every year as you repay and as your WOZ value changes.
How to Use the Dutch Tax Calculator 2026 Mortgage Method
You can see the effect on your salary in four steps:
- Enter your gross income in our Dutch tax calculator.
- Note your estimated net income and tax bracket.
- Calculate your net deduction using the formula above.
- Multiply it by your deduction rate, up to 37.56%.
The result is the extra money you can expect back, often as a lower tax bill or a refund after filing. To understand brackets better, read our Dutch Income Tax 2026 Guide.
Common Mistakes to Avoid
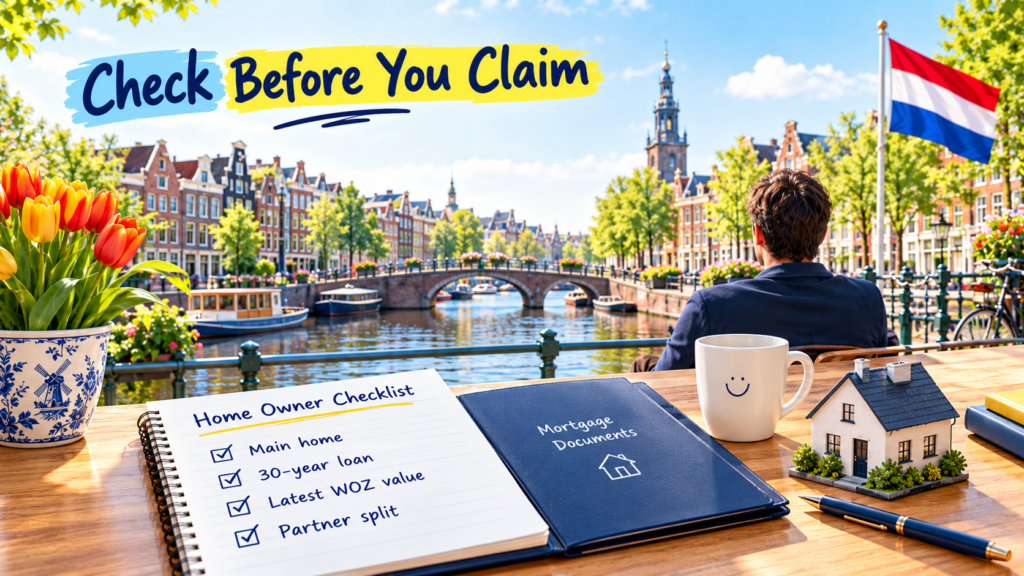
Forgetting the eigenwoningforfait. Many people count the full interest as savings. That makes the benefit look bigger than it is.
Using the wrong rate. Your top bracket may be 49.50%, but the deduction rate is capped at 37.56%.
Ignoring partners. If you own the home together, interest and forfait are usually split between partners. You can often divide them to get the best result.
Outdated WOZ value. Check your latest WOZ notice, because it changes the forfait.
Mixing up the 30% ruling. Expats on the 30% ruling can still claim home deductions, but the bracket they fall in may change the final saving.
What Is Changing After 2026?
The maximum deduction rate follows the second bracket, so it moves when tax rates move. The 2025 rate was 37.48%. For 2027, the government has indicated a small rise to around 38%, which would make the deduction slightly more valuable. The eigenwoningforfait is expected to stay at 0.35% for most homes. Plans can change, so check the Belastingdienst before you decide.
Who Should Be Extra Careful?
Homeowners who have just bought a house, recently remortgaged or paid off part of a loan should recheck their numbers. People who work abroad, own more than one property or earn freelance income should also review their situation. Our methodology page explains how we keep estimates up to date.
FAQ
Is mortgage interest still deductible in the Netherlands in 2026?
Yes, for qualifying loans on your main home, at a maximum rate of 37.56%.
Does the deduction reduce my payroll tax every month?
Yes. You can ask the Belastingdienst for a lower withholding, so you receive the benefit monthly instead of waiting for a refund.
What if my interest is lower than the eigenwoningforfait?
Then you may fall under the Hillen rules, which give a partial benefit. This is being phased out over time, so check the current rules.
Conclusion
A Dutch tax calculator 2026 mortgage check shows that your home can lower your tax bill by thousands of euros a year. Remember the formula: interest minus eigenwoningforfait, multiplied by up to 37.56%. Run your income through our calculator first, then apply your mortgage numbers to see your real take-home pay. This guide is general information and not personal tax advice. For complex cases, speak to a qualified adviser.
John Keller is the founder of Look Forward Administratie & Advies and a Dutch financial administration and tax advisory specialist. With 25 years of experience helping expats, freelancers, and businesses navigate Dutch payroll, income tax, and the 30% ruling, he combines hands-on advisory experience with a focus on making Dutch tax rules understandable for non-Dutch speakers.